Action completed
Back

ब्याज व EMI कैलकुलेटर Pro

Groww Style • प्री-पेमेंट बचत • डिजिटल खाता

गाँव का देसी ब्याज

₹ प्रति सैकड़ा प्रति माह (दिनांक अनुसार या वर्ष/माह/दिन)

₹1,000 ₹10,00,000
₹2 सैकड़ा = 24% वार्षिक
% p.m.
0.5% (₹0.50 सैकड़ा) 5.0% (₹5.00 सैकड़ा)
📅 ऋण लेने की दिनांक (Start Date)
📅 चुकाने की दिनांक (End Date)
कुल देय राशि (Total Payable Amount)
₹0.00
शून्य रुपये मात्र
कुल अनुपात 100%
मूलधन
₹0
कुल ब्याज
₹0
समय अवधि (Duration): 0 दिन
प्रति माह ब्याज (Monthly): ₹0 / माह

📖 ब्याज व लोन EMI कैलकुलेटर गाइड (FAQs)

यह कैलकुलेटर Groww के आधुनिक वित्तीय इंटरफेस के समान तैयार किया गया है, ताकि ई-मित्र कियोस्क, ग्राहक, किसान और दुकानदार सेकंडों में सटीक हिसाब निकाल सकें।

गाँव का देसी ब्याज (सैकड़ा)

₹2 सैकड़ा का अर्थ है ₹100 पर ₹2 प्रति माह (24% वार्षिक)। यहाँ तारीख से तारीख तक दिन के हिसाब से शुद्ध ब्याज निकाला जाता है।

प्री-पेमेंट ब्याज बचत

लोन के दौरान बीच में एकमुश्त अतिरिक्त भुगतान करने से मूलधन घट जाता है, जिससे आगे का ब्याज और किस्तों की संख्या तेजी से कम हो जाती है।

गोल्ड लोन गिरवी ब्याज

सोने के वजन (ग्राम), कैरेट व आज के बाजार भाव अनुसार बैंक या साहूकार से मिलने वाले लोन व मासिक ब्याज का सटीक हिसाब।
Mathematical & Financial Precision

Simple, Compound & Rural Village Interest Explained

Understand the exact mathematical difference between ₹ सैकड़ा monthly interest, bank reducing balance EMIs, and compound interest growth.

RBI Compliant Formulas 100% Private & Offline
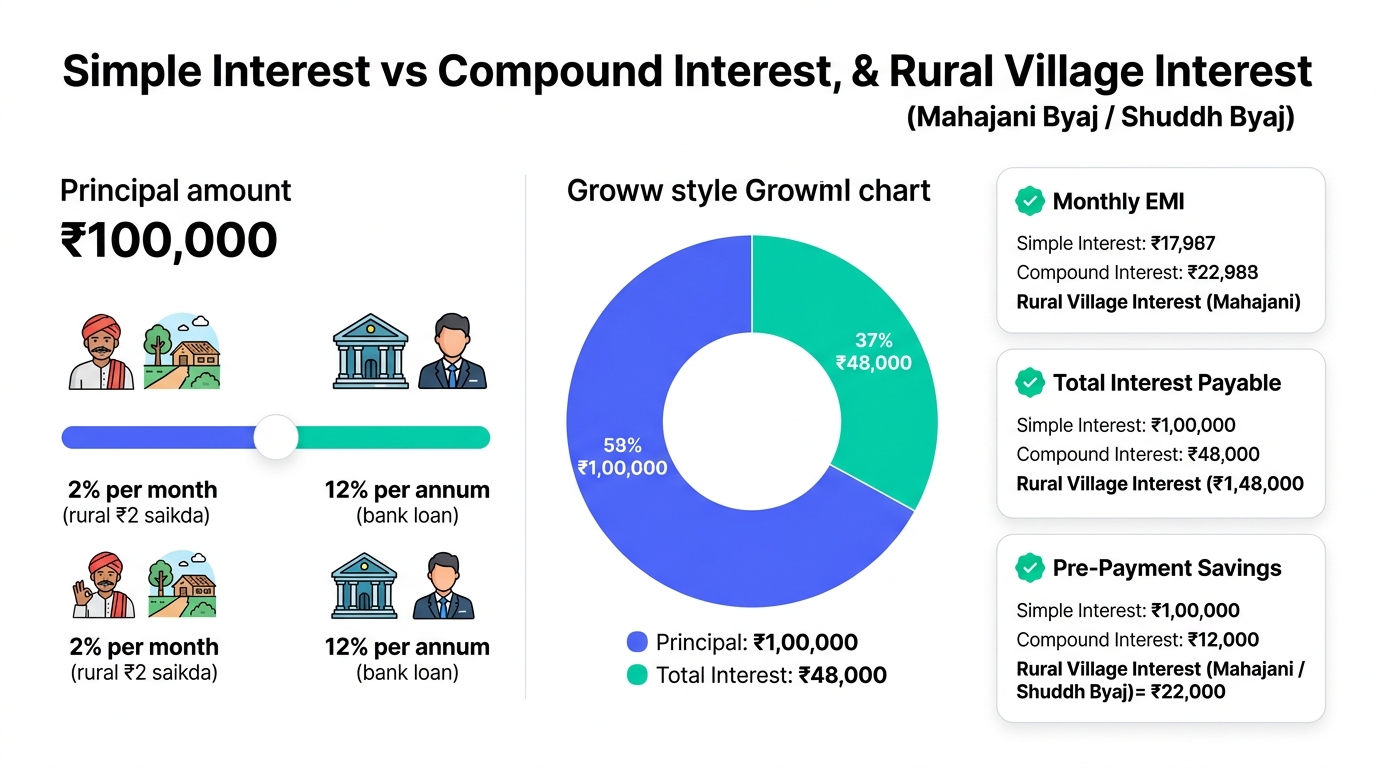
Visual comparison between rural village interest and bank reducing EMI with Groww style doughnut chart

Visual comparison: ₹1,00,000 principal at ₹2 saikda (24% p.a.) vs 12% bank loan with monthly EMI breakdown.

Why Knowing Your True Interest Rate Matters

Many borrowers in rural and semi-urban India confuse monthly interest (e.g. ₹2 or ₹3 सैकड़ा) with annual bank interest rates. A ₹2 monthly interest rate actually equals 24% annual interest! Understanding how interest compounds protects you from debt traps.

Reducing Balance vs Flat Rate

Bank EMIs charge interest only on unpaid principal, whereas flat rates charge interest on the entire original amount throughout.

Prepayment Savings Simulator

Paying an extra lump-sum directly cuts your loan tenure and saves thousands in future interest outgo.

Digital Ledger (हिसाब खाता)

Save borrower calculations directly to your browser's private offline storage and print legal slips anytime.

Step-by-Step Tutorial

How to Calculate Interest & EMI in 4 Steps

Accurate calculations with instant visual breakdown and downloadable receipt.

1

Select Calculator Mode

Choose Rural Village Byaj, Vehicle/Personal Loan EMI, Simple Interest, Compound Interest, or Gold Loan.

2

Set Principal & Rate

Use the interactive range sliders or type the exact amount. Set monthly rate (₹/सैकड़ा) or annual bank rate (% p.a.).

3

Enter Dates or Tenure

Select calendar Start & End dates for exact day-level precision or enter tenure directly in months and years.

4

Save, Share or Print

Inspect the Groww-style doughnut chart, save to Digital Khata, share via WhatsApp, or print a formal slip.

Comparison: Rural Monthly Interest vs Bank Annual Reducing Loan

Side-by-side financial comparison on ₹1,00,000 borrowed for 12 months.

Parameter / Feature Rural Village Byaj (₹2 सैकड़ा) Bank Reducing Loan (12% p.a.) Flat Rate Two-Wheeler (12% p.a.)
Effective Annual Rate 24.0% p.a. (2% × 12) 12.0% p.a. ~21.5% Effective IRR
Monthly Payment / EMI ₹2,000 interest only ₹8,885 / mo (Principal+Int) ₹9,333 / mo
Total Interest on ₹1 Lakh (1 Yr) ₹24,000 ₹6,619 ₹12,000
Total Repayment (Principal + Interest) ₹1,24,000 ₹1,06,619 ₹1,12,000
FAQ

Frequently Asked Questions

Common questions about Indian interest calculation methods, EMIs, and prepayments.

How does rural village interest (₹ सैकड़ा / Desi Byaj) differ from bank interest?

Village interest (Mahajani byaj) is calculated on a monthly basis (e.g. ₹2 per month per ₹100), which equals 24% annual interest (2% × 12). Bank loans are quoted per annum (p.a.) on a reducing balance basis, where interest is charged only on the remaining principal.

What is the difference between Flat Interest Rate and Reducing Balance EMI?

In a flat interest loan (common in two-wheeler finance), interest is computed on the full principal throughout the entire tenure. In a reducing balance loan, interest decreases each month as your principal is repaid, saving thousands in total interest.

How much can I save by making loan prepayments?

Any prepayment directly reduces your outstanding loan principal. By using our Pre-Payment Simulator, you can see how an extra lump-sum payment of ₹25,000 to ₹50,000 can cut months off your loan tenure and save tens of thousands in interest.

Is my digital ledger (हिसाब खाता) stored securely and privately?

Yes! All calculation records and customer names saved in the Digital Khata are stored locally in your browser's LocalStorage. No financial data or customer details are ever uploaded to any cloud server.